If you only talk to your tax professional in March, you’re not doing anything wrong. You’re doing what almost every busy business owner does. You’re running the business, handling payroll, chasing invoices, and tax season is the one deadline that forces the conversation.
But here’s the hard truth that catches people off guard: by the time you’re sitting across from your preparer with a folder of receipts, the year is already written. Your preparer’s job at that point is to report what happened as accurately as possible. It isn’t to change it.
That’s why the return so often feels like a verdict instead of a plan.
Read Also: Understanding The Difference Between Tax Preparation and Tax Strategy
Preparation Looks Backward. Planning Looks Forward.
Tax preparation is documentation. The income is earned, the expenses are booked, the decisions are made. A good preparer will catch every deduction you legitimately qualify for; but they’re working inside a box you already built.
Tax planning happens while the box is still open. It’s asking “what will this cost me?” before you sign the lease, hire the employee, or buy the truck.
The difference isn’t effort or expertise. It’s timing. Most meaningful tax-saving moves have a door that closes on December 31, and some close much earlier than that.
The Decisions That Actually Move the Number
These are the moments where a fifteen-minute phone call can be worth thousands:
- Buying equipment or vehicles. Whether an asset is placed in service on December 28 or January 3 can shift the deduction by a full year. Which year helps you more depends on your income, and that’s a conversation, not a guess.
- Changing your entity structure. Electing S-corp status has a filing deadline early in the tax year, not at filing time. Miss it, and you’re waiting twelve months.
- Setting up a retirement plan. Some plans can be opened after year-end; others must exist well before it. The rules differ by plan type, and the difference is real money.
- A surprise strong year. If Q3 is unexpectedly big, there’s still time to adjust estimated payments, accelerate expenses, or fund a plan. Find out in April, and you’re just writing a check plus penalties.
- Hiring, raises, and owner compensation. Payroll decisions carry payroll tax consequences that compound all year.
- Selling an asset or a piece of the business. Timing and structure here can change the tax bill dramatically.
None of these are exotic strategies. They’re ordinary business decisions that happen to have tax consequences attached, consequences most owners don’t see until it’s too late to respond.
What Ongoing Communication Actually Looks Like
This doesn’t mean monthly meetings or a bigger retainer. For most small businesses, it looks like this:
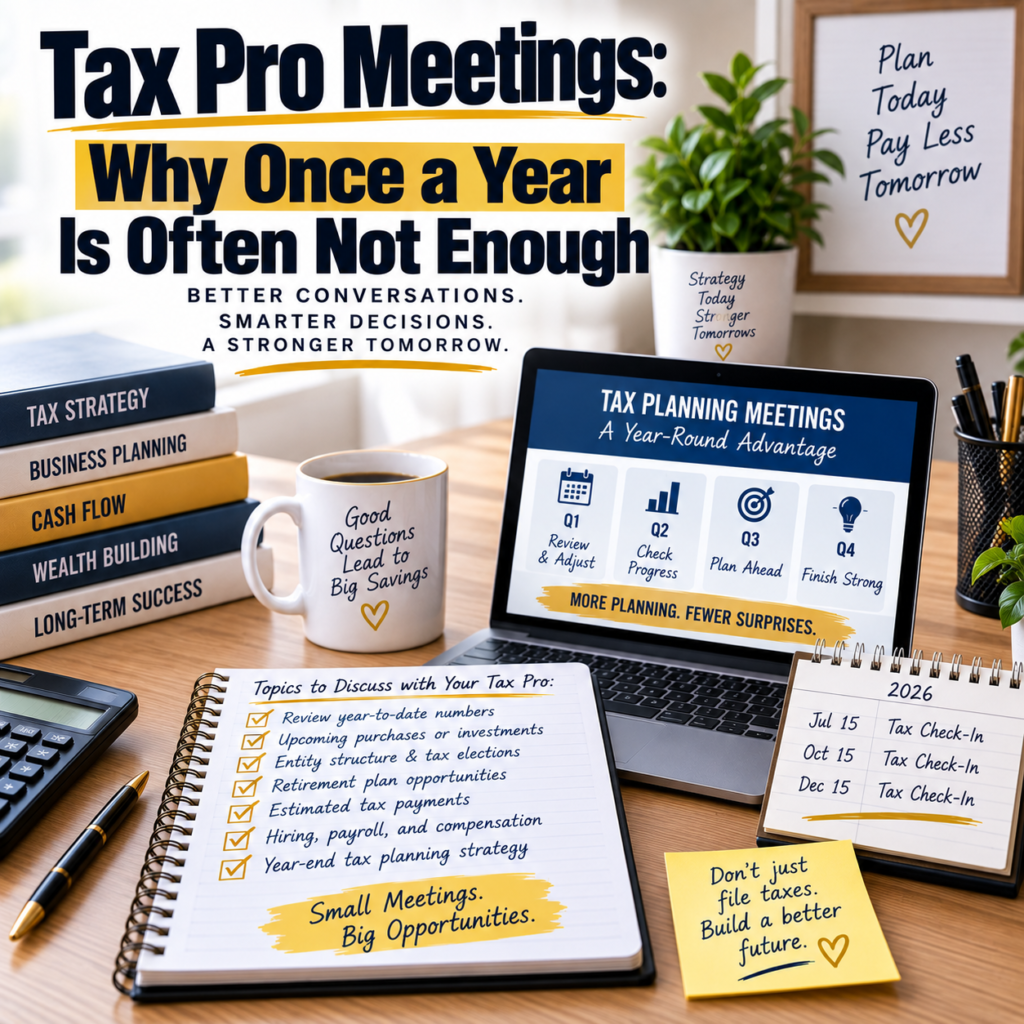
A quarterly touchpoint. Twenty to forty minutes, four times a year. Share your numbers, flag anything big coming up, adjust estimated payments if the year is running hot or cold.
A mid-year check-in (roughly June or July). Enough of the year has happened to see the trend, and enough is left to act on it.
A fall planning call (October or November). This is the highest-value meeting of the year. Everything still on the table gets decided here.
A standing rule: call before, not after. Any decision over a threshold that matters to you, say $5,000, or anything that changes your structure, payroll, or ownership, gets a quick text or email first.
Regular contact also catches problems early. Missed estimated payments, payroll tax issues, and classification mistakes are much cheaper to fix in month three than in month fifteen, when penalties and interest have been quietly accumulating.
Reframing What You’re Paying For
Many owners think of tax fees as the cost of filing. Filing is the smallest part of the value.
What you’re really buying is someone who understands your financial picture well enough to tell you, in advance, what a decision will cost. That only works if they see your numbers more than once a year, and if they’re the kind of professional who wants to.
If your current preparer only surfaces at filing time and has no interest in a mid-year conversation, that’s worth knowing. Many firms offer planning-focused arrangements, and the fee difference is often smaller than the first missed opportunity.
Conclusion
Filing an accurate return is the floor, not the goal. The businesses that consistently pay less, forecast better, and get fewer April surprises aren’t the ones with a better preparer. They’re the ones having the conversation in September, not just in March.
The biggest tax savings are almost always created before the return is filed; not discovered after.
Pro Tip: Put three recurring calendar reminders on your business calendar right now: mid-July, mid-October, and mid-December. Label them “Tax check-in.” In each one, list your top three financial decisions from the past quarter and anything big coming up. Even if you only send that list by email and get a two-sentence reply, you’ll have converted your tax professional from a historian into an advisor, and that single change is where the savings live.
Want to learn more?
Explore the Business Owner Hub
Visit the Business Owner Hub for a guided experience through BizTax Playbook’s free educational resources, calculators, planning strategies, and tools to help you navigate your business journey with confidence.
Join Our Network
Join Our Network to receive educational tips, workflow reminders, tax law updates, deadlines, calculators, and other resources designed to help you make more informed business and tax decisions throughout the year.