On paper, a job offer is just a number. In reality, whether that number comes with a 1099 or a W-2 attached can change what actually lands in your bank account, sometimes by thousands of dollars a year. If you’re comparing two offers, or wondering whether to go independent, this is the part most people skip until tax season forces the issue. Let’s fix that now.
W-2: Taxes Handled For You
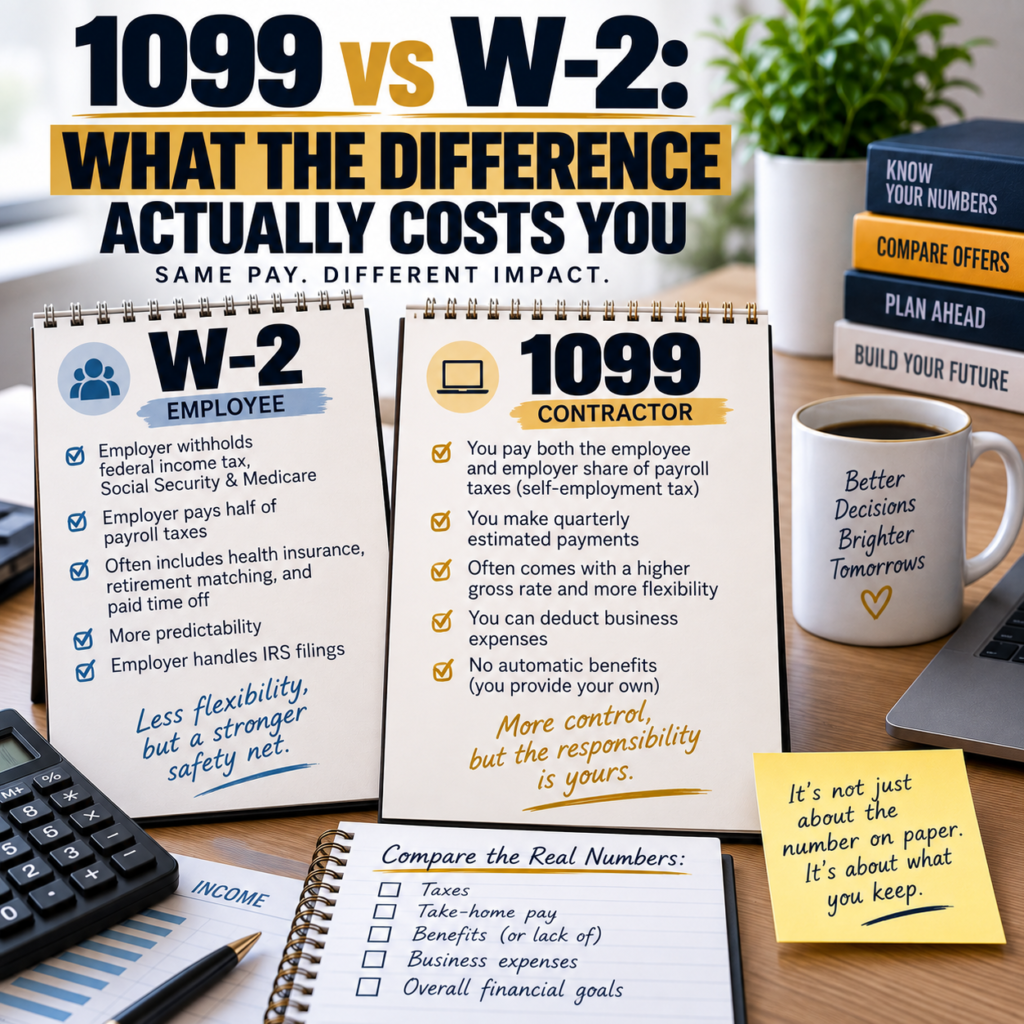
As a W-2 employee, your employer withholds federal income tax, Social Security, and Medicare from every paycheck. They also cover half of your payroll taxes automatically; you never see that money, but you also never have to think about it.
Many W-2 roles also come with health insurance, retirement matching, and paid time off, benefits that have real dollar value even though they don’t show up in your hourly rate.
The tradeoff: less flexibility, but far more predictability. You’re not the one keeping the IRS happy; your employer is.
1099: More Freedom, More Responsibility
As a 1099 contractor, you’re your own tax department. That means paying both the employee and employer share of payroll taxes (self-employment tax), usually through quarterly estimated payments you calculate and send yourself.
In exchange, you often get a higher gross rate, more control over your schedule, and the ability to deduct business expenses. But none of that helps if you haven’t set aside enough for taxes, a common and painful surprise for new contractors.
The tradeoff: more control, but the safety net is yours to build.
The Number That Actually Matters: Net, Not Gross
A $70,000 1099 offer and a $70,000 W-2 offer are not the same $70,000. Once you factor in self-employment tax, the cost of your own health insurance, and lost benefits, the 1099 number often needs to be noticeably higher just to break even with the W-2 offer, let alone get ahead.
This is why comparing offers side by side on gross pay alone can quietly cost you money.
How to Actually Decide
Skip the guesswork. The right choice depends on your specific numbers, your expenses, your state, your benefits situation, not general advice. Before you sign anything or make a switch, run your real numbers so you know exactly what you’re choosing, not just what you’re hoping.
Pro Tip: Don’t leave this to guesswork; plug your numbers into our 1099 vs W-2 Calculator to see the real, side-by-side tax and take-home difference in minutes.
Want to learn more?
Explore the Business Owner Hub
Visit the Business Owner Hub for a guided experience through BizTax Playbook’s free educational resources, calculators, planning strategies, and tools to help you navigate your business journey with confidence.
Join Our Network
Join Our Network to receive educational tips, workflow reminders, tax law updates, deadlines, calculators, and other resources designed to help you make more informed business and tax decisions throughout the year.